Water Damage Insurance Claims in South Carolina: What Is Covered
Filing a water damage insurance claim in South Carolina is confusing at the worst possible moment. This guide explains what homeowner policies typically cover, what they exclude, how flood insurance differs, the exact steps to file, and your rights when the adjuster gets involved. (803) 555-0147
Key Takeaways
- Sudden water damage (burst pipes, appliance failures, storm intrusion) is usually covered by homeowner insurance.
- Gradual leaks, foundation seepage, and rising floodwater are typically excluded - floodwater needs separate flood insurance.
- Documentation decides claims: photos, moisture logs, drying reports, and line-item estimates.
- You choose your contractor - your insurer's preferred-vendor list is optional.
- File fast, mitigate further damage immediately, and never sign away rights you do not understand.
Sudden vs. Gradual: The Distinction That Decides Claims
Insurers draw a hard line between sudden and gradual water damage. Sudden and accidental events – a pipe that bursts, a water heater that ruptures, a washing machine hose that lets go, rain entering through a storm-damaged roof – are typically covered. Gradual damage – a slow leak under a sink that rots the cabinet over months, long-term seepage, maintenance issues you knew about – is typically excluded as a maintenance failure. The practical lesson: fix small leaks fast, and when sudden damage happens, document the timeline clearly. A dated photo trail showing “this happened Tuesday” protects you from a gradual-damage dispute.
Flood vs. Homeowners: Two Different Policies
Standard homeowner policies in South Carolina exclude rising water – river flooding, storm surge, flash-flood runoff that enters from outside. That coverage comes from separate flood insurance, either through the National Flood Insurance Program (NFIP) or a private carrier. But rain entering through wind-damaged roofs or windows during a storm is usually covered under your homeowner policy as windstorm damage. After the October 2015 floods, many Columbia homeowners learned this distinction the expensive way – including some outside mapped flood zones. Review your coverage before storm season, not after. Start at FloodSmart.gov (the NFIP’s official site) and Ready.gov/floods.
Sewer Backups Need Their Own Endorsement
Many homeowner policies exclude sewer and drain backups unless you have added a water/sewer backup endorsement – usually an inexpensive add-on that covers thousands in cleanup. If your Columbia home has aging clay or cast-iron laterals, mature trees near the sewer line, or a history of backups during heavy rain, this endorsement is essential. Check your policy today; after a backup is too late.
How to File Your Water Damage Claim in 7 Steps
Stop the damage and stay safe
Shut off the water source and electricity to affected areas if you can do it safely. Your policy requires you to mitigate further damage - doing nothing can reduce your payout.
Document everything
Photos and video of every affected area, waterlines, damaged belongings, and the source. Written list of damaged items with approximate ages and values. Do this before cleanup where possible.
Call a restoration professional
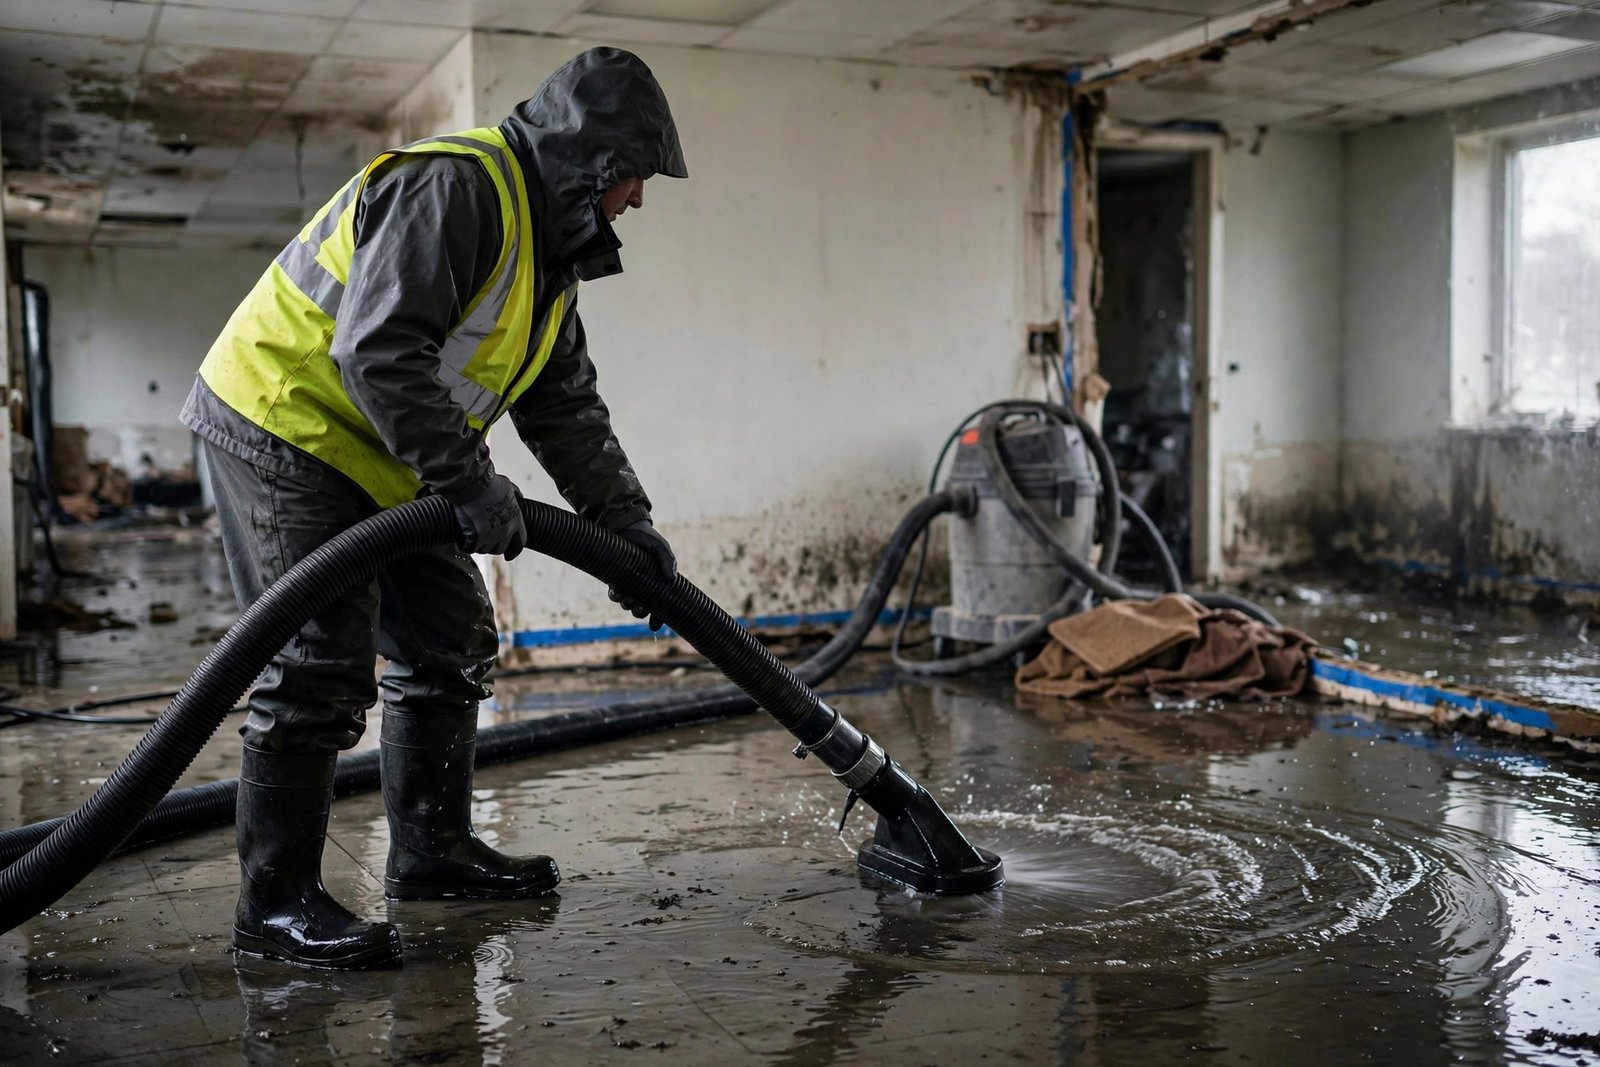
Get crews started on extraction and drying immediately - waiting for the adjuster first is a mistake. We document to adjuster standards from the first visit.
Notify your insurer within 24 hours
Report the claim, get your claim number, and ask about your deductible, coverage limits, and whether emergency services are pre-authorized.
Meet the adjuster with documentation ready
Walk them through with your photos, our moisture reports, drying logs, and the itemized scope. The more professional your documentation, the smoother the approval.
Review the settlement before accepting
Compare the adjuster's scope against the contractor's itemized estimate. Question anything missing - drying days, demolition, sanitizing. You can negotiate and supplement the claim.
Approve repairs only when drying is verified
Do not let anyone rebuild on wet materials. Final repairs start only after moisture readings confirm every material is at dry standard - we provide those readings.
Your Claim Documentation Checklist
Do This Now
- Photograph and video every affected room from multiple angles, including waterlines on walls.
- List every damaged belonging with approximate age and value.
- Save receipts for all emergency spending (hotel, supplies, emergency services).
- Keep a dated log of every call with your insurer: who you spoke to, when, what was said.
- Get the restoration scope in writing, itemized: extraction, demolition, drying days, sanitizing, repairs.
- Request copies of all moisture readings and drying logs for your file.
Don't Do This
- Do not throw away damaged items before the adjuster has seen and documented them.
- Do not sign a direction-to-pay or assignment of benefits you do not fully understand.
- Do not accept the first settlement figure without comparing it to the contractor's itemized scope.
- Do not let repairs begin before drying is verified with moisture readings.
Your Rights: Choosing Your Own Contractor
This matters: your insurance company’s preferred-vendor or “managed repair” list is optional. South Carolina law and standard policy language give you the right to choose your own contractor – no policy can force you to use theirs. Preferred vendors work for the insurer’s cost targets; your contractor works for your home. We document to the same industry standards (IICRC S500) that adjusters expect, so your claim is supported whichever contractor you choose. If an adjuster pressures you toward their vendor, you can politely decline.
How We Support Your Claim
We provide the documentation package adjusters ask for: dated photos, moisture mapping reports, daily drying logs with calibrated readings, and line-item estimates in the formats carriers use. We coordinate directly with your adjuster through the process – answering questions, providing supplements when hidden damage is found, and verifying dry standard before repairs. When your claim allows it, the provider can bill your insurer directly. You approve everything before work proceeds, and you receive copies of every document we generate.
Sources
Sources
- Ready.gov - Floods - Flood insurance and claims guidance.
- FloodSmart.gov - The National Flood Insurance Program's official site.
- U.S. EPA - Mold - Mold guidance relevant to claim documentation.
- IICRC - The restoration industry's standards body (S500 water damage standard).
Frequently Asked Questions
Possibly – it depends on your carrier, your claims history, and your state regulations. One sudden-and-accidental claim is often treated differently than repeated claims. Ask your agent about your specific policy before assuming the worst, and weigh the claim against your deductible.
Report promptly – ideally within 24 hours. Most policies require “prompt” notice, and delays give insurers room to dispute. Mitigate further damage immediately; that duty starts the moment you discover the water.
Ask for the denial in writing with the specific policy language cited. You can appeal, provide additional documentation, request a re-inspection, and in South Carolina you can file a complaint with the SC Department of Insurance if you believe the denial is unfair.
NFIP policies have limited basement coverage – generally structural elements and essential equipment, not finished walls, flooring, or personal belongings in basements. Know these limits before you need them; check FloodSmart.gov for current terms.
No. Your policy requires you to prevent further damage, and mold does not wait for appointments. Start professional mitigation immediately and document everything – photos, readings, logs – so the adjuster sees a complete record.
An assignment of benefits (AOB) transfers your claim rights to the contractor, letting them negotiate and collect directly from your insurer. It can simplify things but you lose control of the claim. Never sign one without understanding exactly what rights you are giving up – ask questions first.
No. Preferred-vendor lists are optional. You have the right to choose your own contractor, and insurers must evaluate your claim on its merits regardless of who does the work.
Filing a claim? Start with documentation done right.
Filing a claim? Start with documentation done right. Call (803) 555-0147 now – 24/7 across Columbia, SC. We document to adjuster standards from the first visit: photos, moisture logs, and line-item estimates.